Market Insights
Australian Unit Prices 2026: The House Premium by Capital City

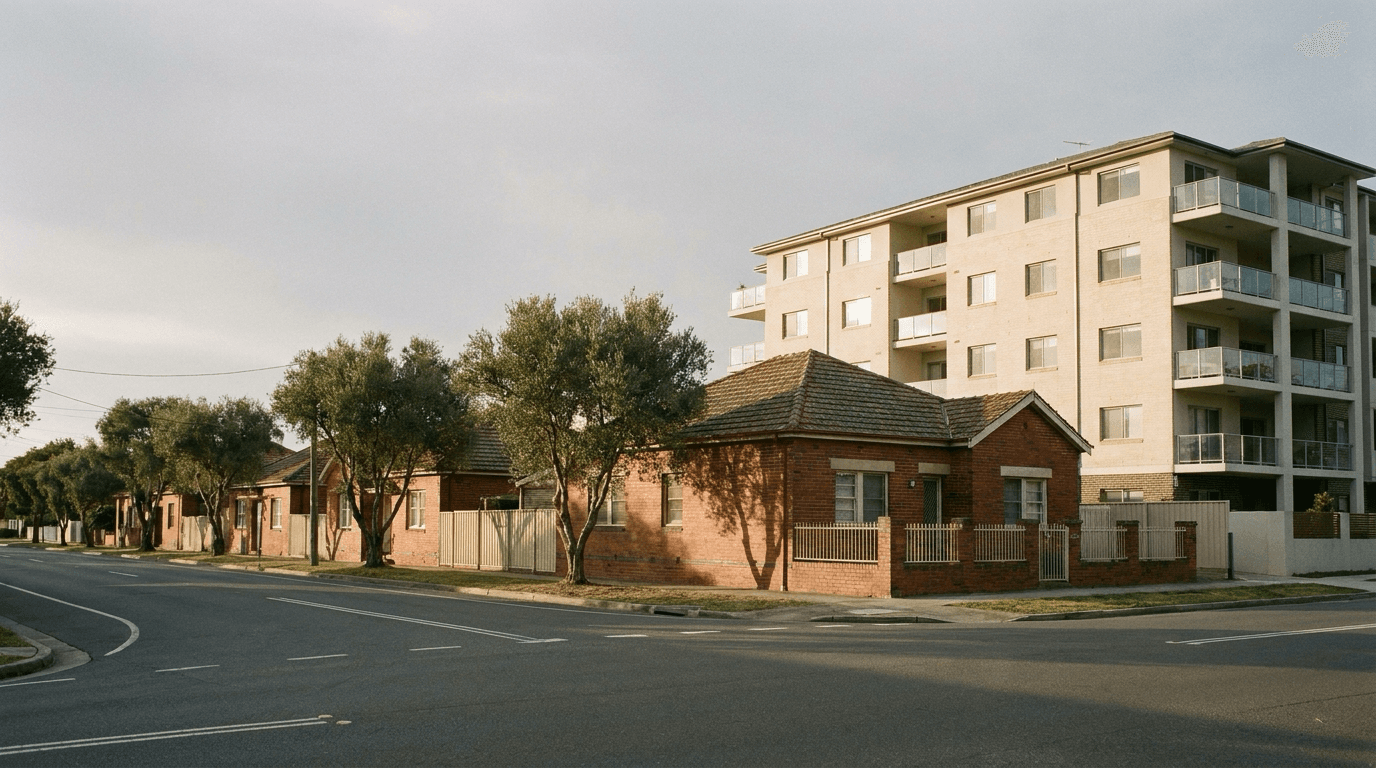
A house and a unit in the same suburb are two different markets, and the distance between them is now the single largest structural feature of Australian residential pricing.
At 30 September 2026, the median house across the combined capitals was $1,103,201 and the median unit $738,778. That is a house premium of 49.3%, or $364,423 in cash. Nationally the gap is narrower — 34.5%, or $251,375 — because regional Australia has far less of a spread.
But the national figure hides a range that runs from a third to nearly three-quarters, depending on which capital you are standing in.
Median unit values and the house premium, by capital
All figures are Cotality Home Value Index medians at 30 September 2026. The premium column is the house median divided by the unit median; the cash column is the difference between them.
| Capital | Median unit | Median house | House premium | In cash |
|---|---|---|---|---|
| Canberra | $582,245 | $1,006,269 | 72.8% | $424,024 |
| Sydney | $867,597 | $1,466,060 | 69.0% | $598,463 |
| Darwin | $480,748 | $747,252 | 55.4% | $266,504 |
| Adelaide | $674,188 | $990,531 | 46.9% | $316,343 |
| Melbourne | $624,740 | $915,119 | 46.5% | $290,379 |
| Perth | $714,265 | $1,017,734 | 42.5% | $303,469 |
| Brisbane | $834,627 | $1,146,078 | 37.3% | $311,451 |
| Hobart | $591,795 | $790,406 | 33.6% | $198,611 |
| Combined capitals | $738,778 | $1,103,201 | 49.3% | $364,423 |
| National | $727,818 | $979,193 | 34.5% | $251,375 |
Two things in that table are worth sitting with.
Canberra, not Sydney, has the widest premium in the country. A Canberra house costs 72.8% more than a Canberra unit — a wider relative gap than Sydney’s 69.0%, even though Sydney’s gap is far larger in dollars. In a leasehold jurisdiction where the unit stock is concentrated and the detached stock is not, the ratio tells you something the dollar figure does not.
Hobart is the closest thing Australia has to a single market. At 33.6%, the premium is less than half Canberra’s. A Hobart buyer choosing between a house and a unit is choosing between $790,406 and $591,795 — a real decision, but not a different financial universe.
When the gap opened
The premium is not a permanent feature of the market. It is recent.
Cotality’s own commentary puts the combined-capitals premium at “just 20%” around October 2020, reaching a series high of 49.9% — about $363,000 — in October 2025. At September 2026 the same calculation gives 49.3%.
So the widening happened across roughly five years to 2025, and has since stopped. The story of 2026 is not a gap that keeps opening; it is a gap that opened, and then held. Anyone writing about this as a current trend is a year late.
Why houses pulled away
Two documented forces, rather than the usual assertions about lifestyle preferences.
The land, not the building. Cotality attributes house outperformance to the associated land value. A detached house is a larger share land and a smaller share structure, and it is land that has carried Australian capital growth. A unit buyer is buying proportionally more building — which depreciates — and less of the thing that appreciates.
Apartment supply collapsed and did not recover. The National Housing Supply and Affordability Council’s State of the Housing System 2026 records higher-density completions at 62,000 in 2025, which is 41.4% below the peak of 106,000 in the year to September 2017. The same report puts 2024–25 build cost at $4,500 per square metre for apartments against $2,000 for detached houses — a gap that makes a great deal of apartment development unviable before it starts.
A market with less new supply might be expected to see prices rise, not lag. That it has not is the clearest evidence that the premium is being driven by the land component, not by the balance of apartment supply and demand.
What the premium buys back
The figure most often left out of this comparison is yield, and it points the other way.
At the combined capitals, gross yield on units is 4.7% against 3.4% on houses — 1.3 percentage points. The spread holds in every capital: Melbourne 5.2% against 3.5%, Darwin 7.5% against 6.0%, Canberra 5.5% against 4.0%.
So the house premium is not free money foregone. A buyer paying 49.3% more for the house is accepting a materially lower income return in exchange for exposure to the land component. Whether that is a good trade depends entirely on whether land continues to do what it has done, which is a forecast rather than a fact — and not one this article will make.
For valuation purposes the practical point is narrower and firmer: a house and a unit in the same postcode are not comparable evidence for one another, and a premium that ranges from 33.6% to 72.8% across the capitals cannot be carried as a rule of thumb from one city to the next.
For context: what the stock looks like
At the 2021 Census — the most recent dwelling breakdown published, with the 2026 figures not yet released — Australia had 10,852,208 private dwellings, of which 70% were separate houses, 13% townhouses and 16% apartments.
Units are therefore a minority of the stock carrying a majority of the affordability conversation, which is worth remembering when national medians are quoted without a dwelling type attached.
Methodology
- All medians are Cotality Home Value Index values at 30 September 2026, taken from the Houses and Units tables of the index release, not from a secondary summary.
- The premium and cash columns are our arithmetic on those medians, computed and checked rather than quoted. Where a published premium figure exists — the 49.9% at October 2025 — it is attributed as published.
- A widely circulated “32.3% national gap” figure was checked and discarded. It could not be verified in any Cotality document, and nothing is published here that we could not trace to the index release itself.
- Completion and build-cost figures are from the National Housing Supply and Affordability Council’s State of the Housing System 2026; dwelling composition is from the 2021 Census.
Frequently asked questions
What is the median unit price in Australia?
At 30 September 2026 the median unit value was $738,778 across the combined capitals and $727,818 nationally, on Cotality Home Value Index medians. Sydney is the most expensive capital for units at $867,597 and Darwin the least at $480,748.
How much more does a house cost than a unit?
Across the combined capitals, 49.3% more — $1,103,201 against $738,778, a difference of $364,423. The premium is widest in Canberra at 72.8% and narrowest in Hobart at 33.6%.
Is the house–unit gap still widening?
No. It widened from around 20% in October 2020 to a series high of 49.9% in October 2025, and at September 2026 it sits at 49.3%. The widening was a 2020–2025 event that has since stalled.
Do units yield more than houses?
Yes, consistently. Gross yield at the combined capitals is 4.7% on units against 3.4% on houses, and the spread holds in every capital city. The house premium is paid for partly in foregone income.
Sources:
- Cotality Home Value Index, index results as at 30 September 2026
- National Housing Supply and Affordability Council, State of the Housing System 2026
- ABS Census of Population and Housing 2021 — dwelling structure
General market information, current at the date of the index release cited. Medians describe a market, not a property: no median is evidence of the value of any particular dwelling, and a valuation requires inspection and comparable evidence specific to the asset. Last verified 8 October 2026.
See also: Australian House Prices 1980–2026 · How Apartments Are Valued · Property Valuation Cost in Australia · Current Market Value · Residential Valuation
About the author
Tajinder Dhillon
Principal Valuer
Tajinder Dhillon is the Principal Valuer at Landmark Valuations, a RICS-regulated property valuation firm. He leads independent valuations across residential, commercial, industrial and rural property throughout Australia.
Connect on LinkedIn