Standards
When a Rezoning Creates Value, Who Takes a Cut — and Who Values It

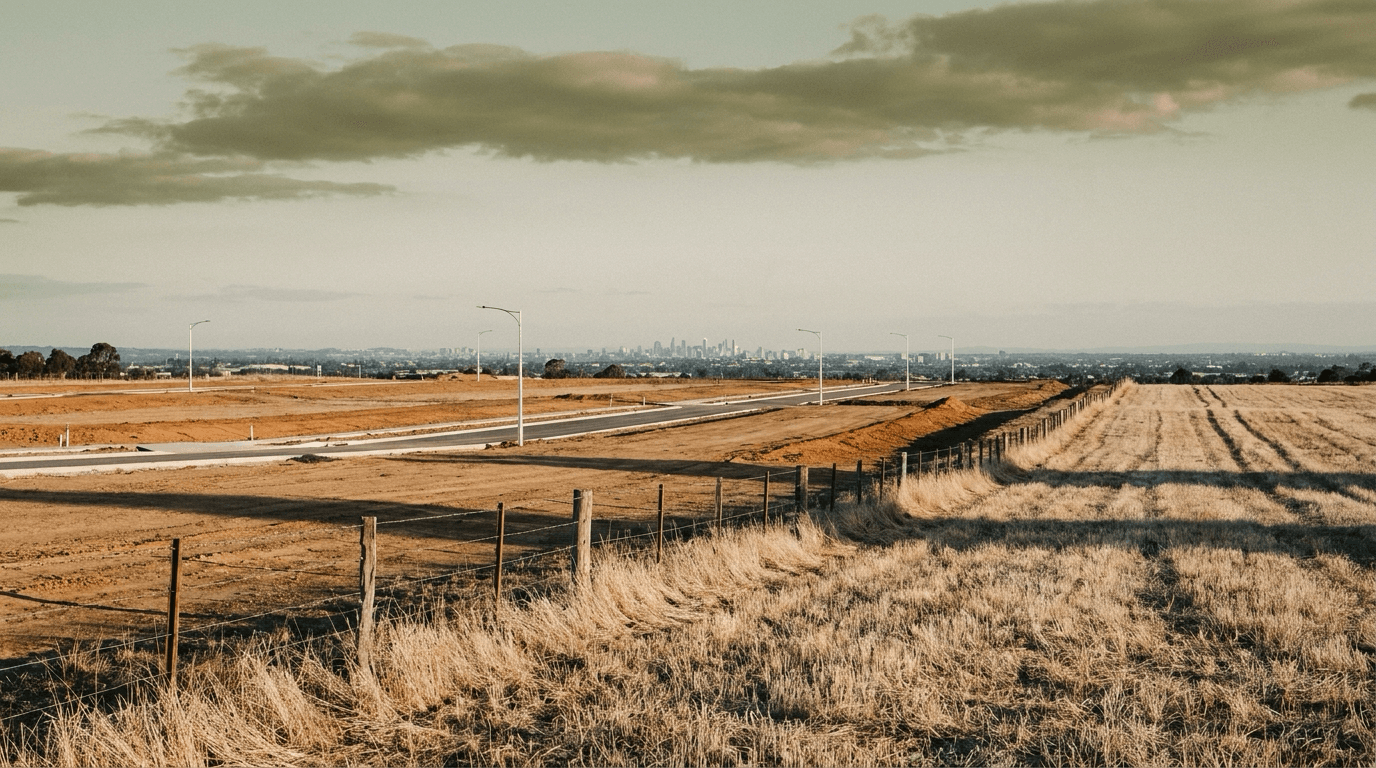
Somewhere on the edge of every Australian capital there is a fence with stubble on one side and graded earth, kerbs and street lighting on the other. Nothing physical moved that line. A planning decision did, and in doing so it changed what the land on one side is worth.
Victoria taxes that change at up to half of it. Most of the country does not tax it at all. The gap between those two positions is the largest unexamined difference in Australian property taxation, and it turns entirely on a valuation — one struck at a date you do not pick, on a basis you may not expect, with a window to challenge it that is shorter than most owners realise.
Quick reference — what each jurisdiction charges on a rezoning uplift
Two jurisdictions take a share of the value a planning decision creates. Six do not:
| Jurisdiction | What it charges on a rezoning uplift | How the number is set |
|---|---|---|
| Vic | Windfall Gains Tax — up to 50% of the whole uplift | Valuation: CIV2 − CIV1 |
| ACT | Lease Variation Charge on a variation of a Crown lease | Codified schedule, or (V1 − V2) × 75% |
| WA | No charge on rezoning. A 50% betterment provision exists at s 184 of the Planning and Development Act 2005, but it is triggered by scheme works, not by a rezoning | — |
| NSW | None. Infrastructure contributions only (ss 7.11, 7.12, and the Housing and Productivity Contribution) | — |
| Qld | None. Infrastructure charges only | — |
| SA | None. Infrastructure contributions only | — |
| Tas | None. Negotiated agreements only | — |
| NT | None. Infrastructure contributions only | — |
Victoria: a tax on the planning decision, not on the market
Victoria’s Windfall Gains Tax Act 2021 has applied since 1 July 2023. The rate sits in a three-row table at s 9, and the shape of it matters more than the headline:
| Taxable value uplift | Tax |
|---|---|
| Not more than $100,000 | Nil |
| More than $100,000 but less than $500,000 | 62.5% of the part above $100,000 |
| $500,000 or more | 50% of the whole uplift |
The two bands meet exactly: just under $500,000, 62.5% of the roughly $400,000 above the threshold approaches $250,000, and at $500,000 exactly, 50% of the whole is $250,000. There is no cliff at the crossover — the design is deliberate.
None of these figures is indexed. We checked the Act for every adjacent mechanism — indexation, CPI, consumer price, adjust, vary, escalate, inflation, annually, each financial year — and found none. Section 44 lets regulations prescribe what the Act requires or permits to be prescribed, and the s 9 amounts are not among them; there is no Gazette power either. They move only when Parliament amends them, which means the $100,000 threshold set in 2021 catches more rezonings with every year of land-price growth.
What is actually valued
Section 10 defines the taxable value uplift as “the value uplift of the land less any deductions prescribed by the regulations” — and as at 5 October 2026 no regulations have been made under the Act, so in practice there are no deductions. Section 11 then reduces the whole thing to a subtraction: CIV2 minus CIV1.
CIV is capital improved value, not site value. The distinction is not cosmetic: the phrase “site value” appears nowhere in the Act, while “capital improved value” appears seven times. Under the Valuation of Land Act 1960 it is the sum the land “might be expected to realize at the time of valuation” held unencumbered in fee simple.
The technical heart of it is s 13Q(2) of the Valuation of Land Act, which directs the valuer to “assess the value that the land would have had if, at the time at which the last valuation was made, it had been zoned in accordance with the rezoning”. Both figures are struck at the same date. Only the zoning differs. So the tax captures the planning decision and nothing else — not the market movement since, not the value a developer later adds. Whatever the land does afterwards, the taxed number was fixed the moment the zone changed.
The deadline that decides whether you can argue
The Windfall Gains Tax Act contains no objection right at all — no occurrence of objection, review, appeal, VCAT or Tribunal. Challenges run through two other Acts, and they are not on the same clock:
| What you are disputing | Under | Time limit | Extension |
|---|---|---|---|
| The assessment — liability, an exemption, grouping | Taxation Administration Act 1997, s 96(1)(a) | 60 days from service (s 99(1)) | Yes — s 100, at the Commissioner’s discretion, up to 5 years. A refusal is not reviewable (s 100(4)) |
| The valuation on rateable or leviable land | Valuation of Land Act 1960, s 16(6AB) | 2 months after receiving the notice (s 18(c)) | None |
| The valuation on non-rateable, non-leviable land | Taxation Administration Act 1997, s 96(1)(cb) | 60 days (s 99(1)) | None — expressly excluded (s 100(5)) |
That middle row is the one that costs people money. The number the whole tax is calculated from carries the shortest window and no power to extend it — we searched the Valuation of Land Act for extend, out of time, late objection, further time, longer period, may permit, waive, dispense, discretion and special circumstance, and found nothing.
One detail worth having right: the State Revenue Office describes the window as two months “of the issue date”. Section 18(c) says after receiving the notice. Where they diverge, the Act governs, and the difference is however long the post takes.
The exemption most owners will reach for is s 37(1), which covers residential land — which s 36 requires to carry a residence, not merely a residential zoning — “whether on one or more titles”, up to 2 hectares, where it is the only such land of the taxpayer’s that the rezoning touches. Above 2 hectares the relief is not lost: s 37(2) cuts the taxable uplift on each title to VU × (RL − 2) / RL. A bare paddock in a residential zone does not qualify at all.
Deferral is available, and it is not relief
Section 31(1) allows up to 100% of the liability to be deferred. Section 32(1) then brings it due within 30 days of a dutiable transaction or a relevant acquisition, or 30 years after the event, whichever occurs first. The State Revenue Office is explicit that it “can be deferred with interest”. Deferring buys time on the cash, not on the debt.
The ACT: the same question, asked of a lease
Canberra cannot rezone your freehold, because you do not have any. The Territory is leasehold, so the equivalent event is a variation of a Crown lease — and the charge that follows it is the Lease Variation Charge.
It has moved house. The LVC left the Planning and Development Act 2007 when the Planning Act 2023 commenced on 27 November 2023, and now sits in that Act at Chapter 10, Part 10.7, Division 10.7.3 (ss 327–346); we read republication 12, effective 1 October 2026. That Division carries a note doing a lot of work: “This division is a tax law under the Taxation Administration Act 1999.” The charge is administered as a tax, with a tax law’s objection machinery behind it.
The trigger is wide. Section 327 defines a chargeable variation of a nominal rent lease as any variation, with three narrow carve-outs — adjusting a common boundary between adjacent leases of the same permitted use, removing a lease’s concessional status, and anything prescribed by regulation. And s 328(1) gives the rule its teeth: the planning authority “must not execute a chargeable variation of a nominal rent lease unless” the charge has been paid or deferred. The lease simply does not change until the Territory is paid.
Timing is fixed early: under s 329(2) the charge is worked out as at the day the development application is approved, and under s 329(4) the assessed liability “only becomes payable if the territory planning authority executes the variation of the lease”.
Two ways to arrive at the number
The codified schedule (s 331). The Treasurer determines set amounts for standard variations — a figure per additional dwelling, and a figure per square metre of additional non-residential gross floor area. Two constraints are worth knowing, because they are what makes the schedule defensible: the Treasurer must “obtain advice from an accredited valuer at least once every 3 years” (s 331(3)), and the determination must “as far as is practicable, represent the average market value in relation to the standard chargeable variation” (s 331(4)(a)).
Average market value. The schedule is built to be right across a population of sites, which is another way of saying it will be wrong on any particular one — in both directions.
The valuation (s 332). For variations outside the schedule the charge is a formula:
LVC = (V1 − V2) × 75%
where V1 is the capital sum the lease might be expected to realise if it were varied as proposed and offered for sale immediately after the variation, and V2 is the same sum if the lease were not varied and were offered immediately before. Same lease, same moment, one planning change between them — structurally the same question Victoria asks, answered on a lease rather than on a fee simple, and with a quarter of the uplift left with the lessee.
Nobody chooses between the two. The method follows the classification of the variation, not a preference: a variation is standard if it is prescribed by regulation (reg 75 of the Planning (General) Regulation 2023), and s 327 then flips even a standard variation into the non-standard column “if no lease variation charge is determined for the variation under section 331”. Prescribed and priced means the schedule; anything else means a valuation. There is no lessee election.
One live concession is worth knowing, and it is narrower than it sounds. DI2026-143 reduces the charge by 50% — but only on a standard chargeable variation adding dwellings in RZ1 or RZ2, never on the s 332 valuation path, and only where the development application is approved before 30 June 2029, a s 342 deferral was applied for on or after 10 June 2026 and approved, and a certificate of occupancy issues for every dwelling by 31 December 2030. The date that governs planning is the 2029 approval cut-off, not the 2030 expiry.
The rest of the country: contributions are not a share of the uplift
Everywhere else, a rezoning that doubles the value of a paddock produces no tax on the doubling. What the other jurisdictions collect instead are infrastructure contributions — New South Wales under ss 7.11 and 7.12 of the Environmental Planning and Assessment Act 1979 plus the Housing and Productivity Contribution, Queensland under its infrastructure charges regime, and South Australia and the Northern Territory under their own contribution frameworks. Tasmania relies on negotiated agreements. And in New South Wales, Queensland, South Australia and Tasmania, whatever a planning agreement negotiated alongside the rezoning extracts is bargained rather than calculated — and still not a tax.
The distinction is not pedantic, and it is the one most commentary blurs. A contribution is a payment towards the roads, drains and open space the development will use. A betterment tax is a share of the gain itself. One is sized by what the infrastructure costs; the other by what the owner made. A developer can forecast the first from a published schedule before buying. The second depends on a valuation nobody has done yet.
Western Australia is the interesting near-miss. Section 184 of the Planning and Development Act 2005 does provide for betterment at 50% — but it bites when scheme works increase the value of land, not when a rezoning does. The statutory machinery exists; the rezoning trigger does not.
Where this lands for an owner
Three practical consequences follow from the structure, and none of them is obvious from the tax rate.
The number is set before you do anything. Victoria values both sides at the same date, with only the zoning changed; the ACT strikes the charge as at the day the development application is approved. Neither waits to see what you build or what the market does. Rezoned land that then falls in value is still taxed on the uplift the rezoning created.
The valuation is the whole tax. In Victoria the liability is a subtraction between two capital improved values, with no prescribed deductions because no regulations have ever been made. There is no second lever. If the figure is wrong, everything downstream of it is wrong.
The window to say so is short and, for the valuation, unextendable. Two months from receipt in Victoria on the valuation itself, with no power to extend, against sixty days and up to five years of discretion on the assessment. An owner who spends the first month deciding whether the number feels high has spent half of it. This is the point at which an independent retrospective or current market valuation earns its cost — not after the objection period closes, which is when most people first look for one.
Methodology
- Legislation read in its current consolidation, named: Windfall Gains Tax Act 2021 (Vic) version 010, in force 1 July 2025, with the amendment table checked and no 2025–26 amendments or pending bills found; Planning Act 2023 (ACT) republication 12, effective 1 October 2026.
- Absences were tested on neighbouring vocabulary, not one word. The finding that Victoria’s thresholds are unindexed rests on a sweep for indexation, CPI, consumer price, adjust, vary, escalate, inflation, annually and each financial year — none of which carries an indexation mechanism. The per-state findings rest on full-text searches for betterment, uplift, value capture and windfall, not on the word “betterment” alone.
- Extension powers were sought for every deadline reported. The conclusion that the Victorian valuation objection cannot be extended comes from searching the Valuation of Land Act 1960 for extend, out of time, late objection, further time, longer period, may permit, waive, dispense, discretion and special circumstance.
- One divergence is reported rather than smoothed. The State Revenue Office describes the valuation objection window as two months from the “issue date”; s 18(c) says “after receiving” the notice. We follow the Act.
- Arithmetic checked mechanically. The claim that the two Victorian bands meet exactly at $500,000 was computed, not asserted.
Frequently asked questions
What is the windfall gains tax rate in Victoria?
Nil on an uplift of $100,000 or less. Between $100,000 and $500,000, 62.5% of the part above $100,000. At $500,000 or more, 50% of the whole uplift — not just the part above the threshold. The figures are set in s 9 of the Windfall Gains Tax Act 2021 and are not indexed.
Can I object to the valuation the tax is based on?
Yes, but not under the Windfall Gains Tax Act, which contains no objection right. A valuation on rateable or leviable land is objected to under s 16(6AB) of the Valuation of Land Act 1960, within two months after receiving the notice, and there is no power to extend that period. Objecting to the assessment itself is a separate path with a different clock.
Does my state tax the uplift from a rezoning?
Only Victoria taxes a rezoning uplift directly. The ACT charges for a variation of a Crown lease, which is the leasehold equivalent. New South Wales, Queensland, South Australia, Tasmania and the Northern Territory levy infrastructure contributions, which are not a share of the gain. Western Australia has a 50% betterment provision triggered by scheme works rather than rezoning.
How is the ACT Lease Variation Charge calculated?
Either from the Treasurer’s codified schedule for standard variations, or, for everything else, as (V1 − V2) × 75% — the lease’s value after the variation less its value before. The lessee does not choose between them; the classification of the variation decides.
Sources:
- Windfall Gains Tax Act 2021 (Vic) — Victorian legislation
- Windfall gains tax — State Revenue Office Victoria
- Valuation of Land Act 1960 (Vic)
- Taxation Administration Act 1997 (Vic)
- Planning Act 2023 (ACT) — ACT legislation register
- Planning (General) Regulation 2023 (ACT)
- Environmental Planning and Assessment Act 1979 (NSW)
- Planning and Development Act 2005 (WA)
General information about how Australian jurisdictions treat the value a rezoning creates, as it bears on valuation. Not legal, financial or tax advice, and not a full summary of any Act. Liability turns on the land, the zone, the dates and the jurisdiction — confirm your position with your solicitor and tax adviser. Last verified 5 October 2026. We update this article when the legislation changes.
See also: Leasehold Property Valuation in Canberra · Development Feasibility Valuations · Current Market Value · Rural & Agribusiness Valuation · Capital Improved Value vs Market Value
About the author
Tajinder Dhillon
Principal Valuer
Tajinder Dhillon is the Principal Valuer at Landmark Valuations, a RICS-regulated property valuation firm. He leads independent valuations across residential, commercial, industrial and rural property throughout Australia.
Connect on LinkedIn